Personal Finance Tips for 2026: A Practical Guide to Building Real Wealth
Managing money well is less about luck and more about habits. The best personal finance tips for 2026 focus on small, repeatable actions that compound over time. Whether you are paying down debt, building savings, or planning your first investment, a clear system beats willpower every single day.
This guide walks you through a framework that works for ordinary budgets and busy schedules. We will cover budgeting, emergency funds, debt payoff, saving automation, and how modern tools make the whole process easier. The goal is simple: keep more of what you earn and make it grow.
Why a Written Budget Still Wins in 2026
A budget is not a punishment. It is a plan that tells your money where to go before the month runs away from you. People who track spending consistently save more, full stop. According to the U.S. Consumer Financial Protection Bureau, households that write down goals are measurably more likely to reach them.
Start with the classic 50/30/20 split. Put 50 percent of take-home pay toward needs, 30 percent toward wants, and 20 percent toward savings and debt. Adjust the ratios to fit your reality, but keep the structure. The structure is what protects you in a tight month.
How to Set Up Your First Budget
- List every source of monthly income after taxes.
- Write down fixed costs: rent, utilities, insurance, loan payments.
- Estimate variable costs: groceries, fuel, dining, subscriptions.
- Assign every remaining dollar a job, including savings.
- Review the plan weekly and adjust without guilt.
If you own a rental or manage property, the same discipline applies to your operating accounts. Working with an experienced local team can help you separate personal and business cash flow so your budget stays honest.
Build an Emergency Fund Before Anything Else
An emergency fund is the foundation of a calm financial life. Aim for one starter month of expenses first, then grow toward three to six months. This buffer keeps a surprise car repair or medical bill from turning into high-interest debt.
Keep the money in a high-yield savings account that is separate from your checking. Online banks routinely pay far more than traditional branches. The gap between a 0.01 percent account and a 4 percent account on 10,000 dollars is roughly 400 dollars a year for doing nothing.
Smart Personal Finance Tips for Paying Down Debt
Debt quietly drains your future. Two proven methods help you escape it faster. Pick the one that matches your personality and stick with it.
| Method | How It Works | Best For |
|---|---|---|
| Debt Snowball | Pay smallest balance first for quick wins | People who need motivation |
| Debt Avalanche | Pay highest interest rate first to save money | People who want the math optimized |
| Balance Transfer | Move debt to a 0 percent intro card | Strong credit and a payoff plan |
Whichever route you choose, stop adding new balances while you repay. The average credit card rate in 2026 still hovers well above 20 percent, so every dollar of principal you clear is a guaranteed return few investments can match.
One Original Tip That Accelerates Progress
Make a half payment on the day you get paid and the other half two weeks later. This simple trick creates one extra payment per year and reduces the interest that accrues between billing cycles. It costs nothing and quietly shortens your payoff timeline.
Automate Saving So You Never Feel It
Willpower fades, but automation does not. Set up an automatic transfer to savings the day after payday. When the money moves before you can spend it, saving becomes the default instead of the exception.
Pair automation with clear goals. Name each savings bucket: Emergency, Travel, New Laptop, Down Payment. Labeled goals feel real and are far harder to raid on impulse. The Federal Reserve notes in its household economics research that goal-based saving improves follow-through, as detailed by the Federal Reserve.
Use the Right Apps to Stay Consistent
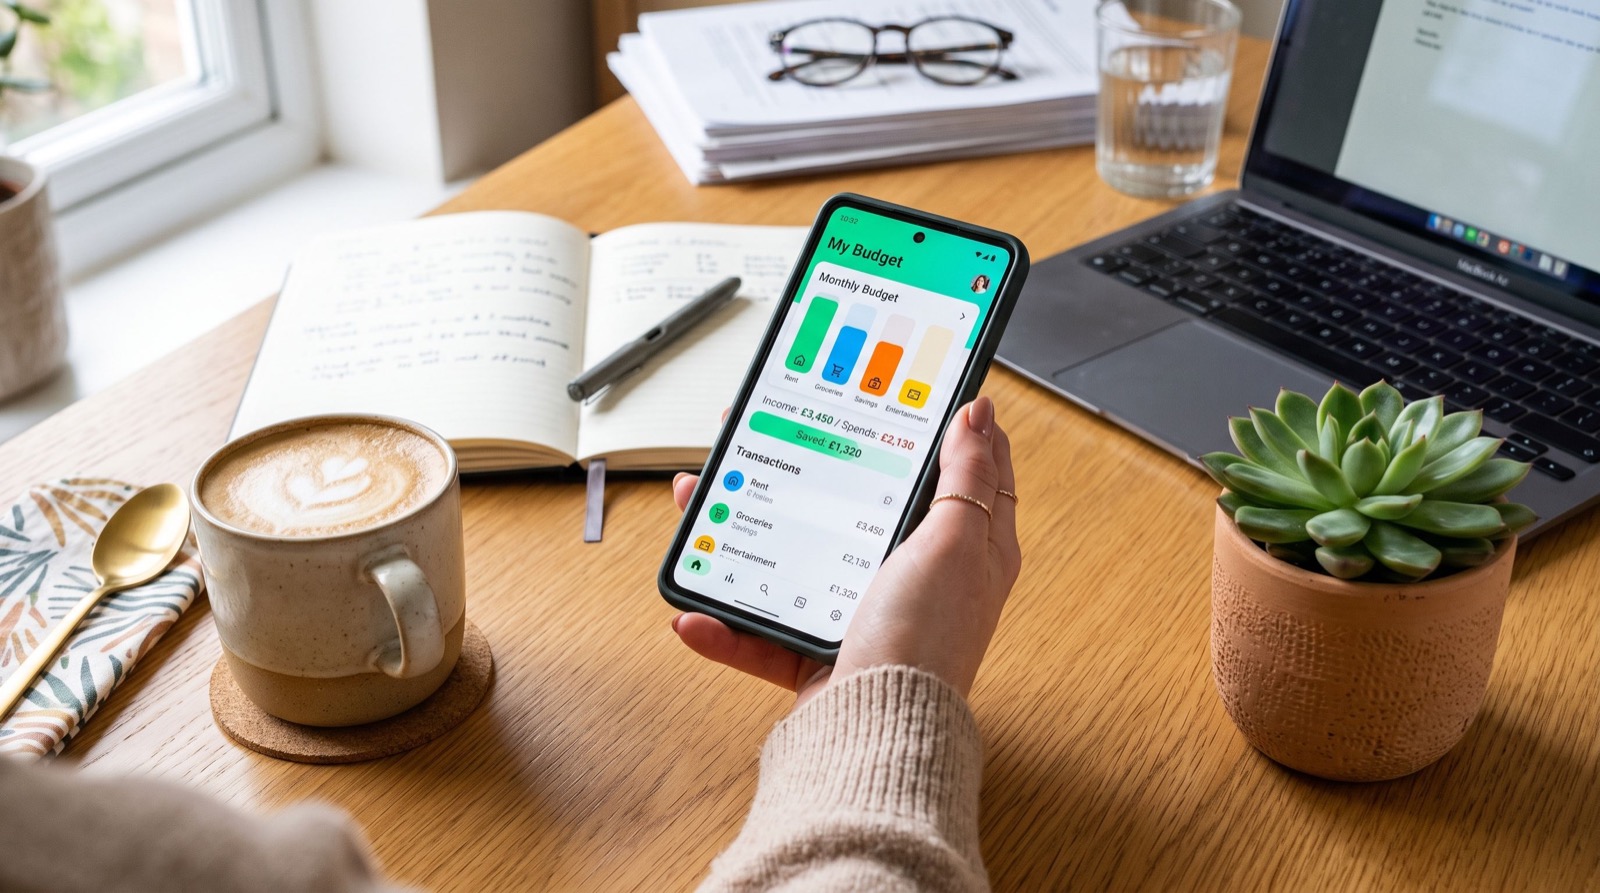
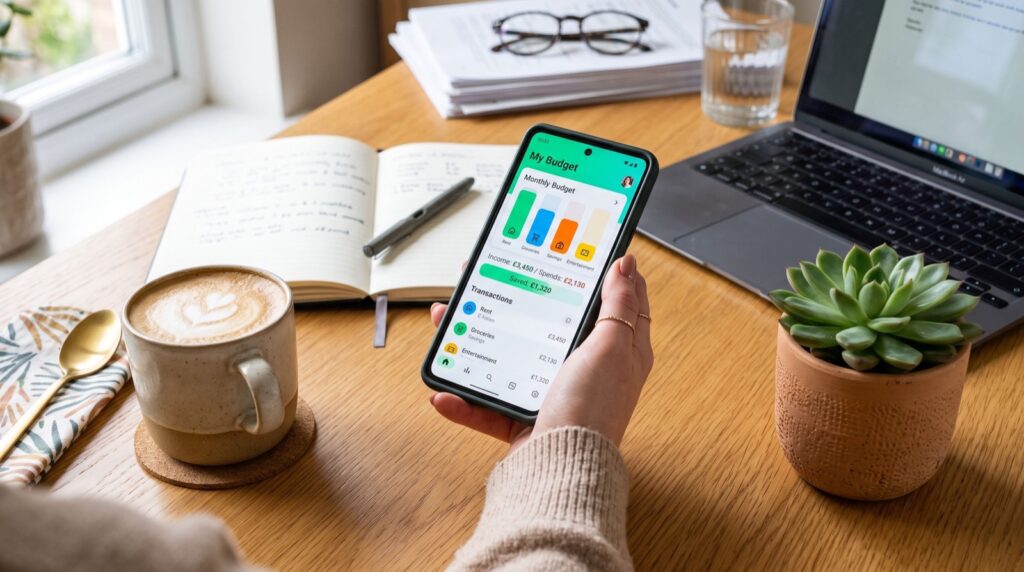
Technology removes friction, and friction is the enemy of good habits. The best money apps let you track spending, round up purchases into savings, and see your net worth in one glance. Choosing from a shortlist of best money apps can turn a weekend budgeting chore into a two-minute daily check.
Look for tools that sync securely with your accounts, send gentle alerts, and categorize transactions automatically. If you want deeper reviews and comparisons, resources that focus on practical personal finance tips can help you match an app to your specific goals.
What Features Actually Matter?
- Bank-level encryption and two-factor login.
- Automatic categorization you can edit.
- Bill reminders to avoid late fees.
- Clear reports you will actually read.
- No hidden fees that eat your savings.
Invest Early, Even With Small Amounts
You do not need thousands to start investing in 2026. Many brokerages allow fractional shares, so 25 dollars a week can buy a slice of a diversified index fund. Time in the market matters more than timing the market.
Prioritize any employer retirement match first, since that is an instant 100 percent return. Then fund a tax-advantaged account before a regular brokerage. Keep fees low and your strategy boring, because boring and consistent usually wins.
Track Your Progress and Celebrate Milestones
Motivation fades when progress feels invisible. Give yourself a simple scoreboard and review it on the same day each month. Watching your net worth climb and your debt shrink keeps you committed far longer than vague hope ever could.
Set milestones that trigger a small, planned reward. Paying off a credit card or reaching a savings target deserves recognition, as long as the reward does not blow the budget. Positive reinforcement turns a chore into a habit you actually enjoy.
A Simple Monthly Review Checklist
- Update your net worth figure and compare it to last month.
- Confirm every automatic transfer and bill payment went through.
- Scan for any new subscriptions or fees that crept in.
- Adjust next month’s category limits based on what you learned.
- Note one win, however small, to keep your momentum high.
Over a year, these quick reviews compound into serious clarity. You stop reacting to money surprises and start steering your finances with intention. That shift in mindset is where lasting wealth really begins.
Frequently Asked Questions
What is the single most important personal finance tip?
Spend less than you earn and automate the difference into savings. Every other strategy builds on that one habit, and automation makes it stick without daily effort.
How much should I keep in an emergency fund?
Start with one month of essential expenses, then build toward three to six months. Store it in a high-yield savings account so it stays accessible and earns interest.
Are budgeting apps safe to use?
Reputable apps use bank-level encryption and read-only access to your accounts. Enable two-factor authentication, use a unique password, and avoid tools that are vague about security.
Should I pay off debt or invest first?
Capture any employer retirement match first, then attack high-interest debt above roughly 7 percent. Once that debt is gone, shift your energy toward long-term investing.
Conclusion and Next Steps
Lasting results come from systems, not sudden bursts of motivation. The personal finance tips in this guide work because they are simple, repeatable, and automated. Pick one action today, whether that is drafting a budget, opening a high-yield account, or starting an automatic transfer.
Build your buffer, crush your debt, and let small investments grow quietly in the background. Choose the right tools, review your plan monthly, and your future self will thank you. Start now, stay consistent, and watch your money finally work for you.